Note, 1 min read
Container lines' best quarter is already behind them
Second-quarter profits rode the disruption. The return to Suez is releasing capacity into a market with almost 14 million TEU on order.
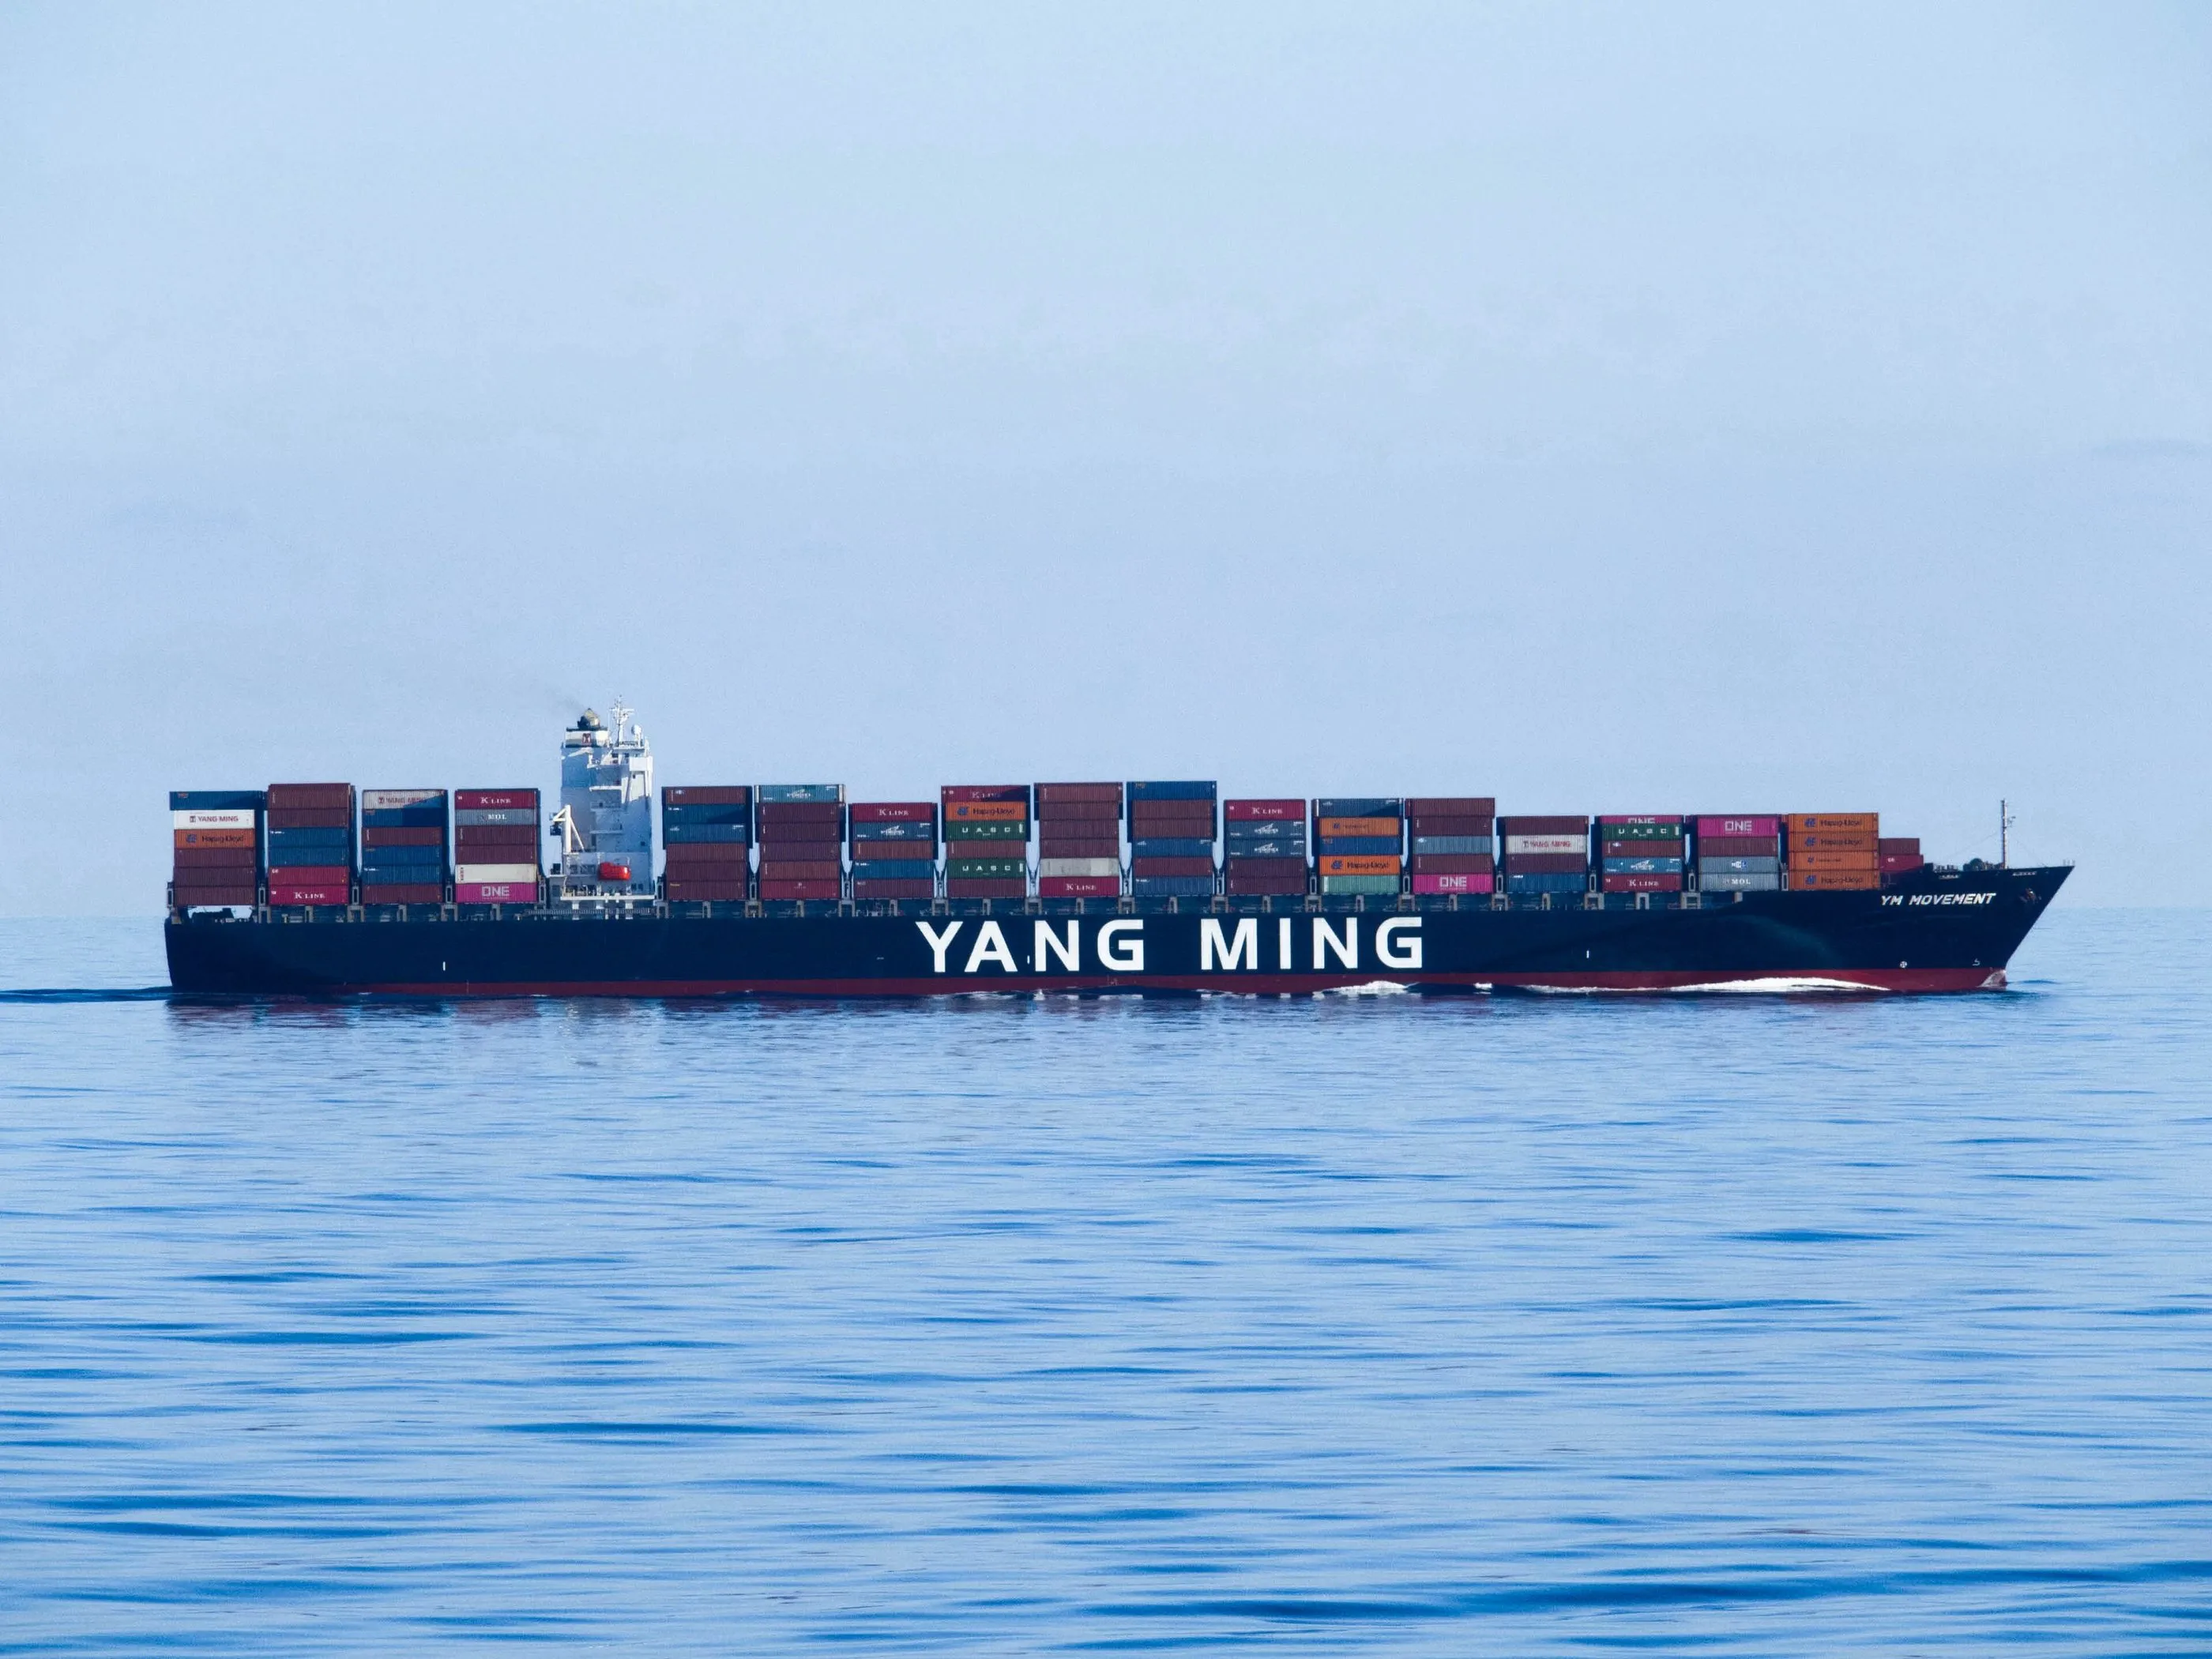
A Yang Ming container ship in the Mediterranean, bound for the Suez Canal, October 2018. RH, CC BY-SA 4.0.
Maersk Ocean EBIT, Q2 $935m ($229m a year earlier) . WorldCargoNewsMaersk’s Ocean division earned $935 million before interest and tax in the second quarter, against $229 million a year earlier and a $192 million loss in the first quarter. The eight carriers that reported EBIT made a combined $2.69 billion, up 58%, on Sea-Intelligence figures compiled by WorldCargoNews. CMA CGM credited “higher transported volumes and stronger freight rates amid geopolitical disruptions”.
Drewry World Container Index $4,468/40ft, -1% w/w . Drewry, via DCNThe disruption is now unwinding through the carriers’ own routing decisions. Drewry counted Suez Canal transits rising from 41 in week 37 to 48 in week 38, “adding effective capacity on the Asia-Europe trade route.” Its World Container Index fell 1% to $4,468 per forty-foot container on 24 September, with Shanghai-Rotterdam down 4% to $3,485. Drewry expects rates to keep falling because “recovering effective capacity outweighs blank sailings,” even with seven sailings cancelled for the following week, up from three.
Behind the returning capacity sits a large orderbook. Alphaliner counts almost 14 million TEU on order, roughly two-fifths of a fleet of 34.8 million TEU. Sea-Intelligence estimates that delays still tie up around 5% of deep-sea capacity, 1.7 million TEU, which comes back as congestion eases.
Valtor’s inference Our reading, and it is an inference: the second quarter was earned on capacity that the long way round the Cape of Good Hope absorbed. Each service that returns to Suez hands some of that capacity back to the market as the newbuilds arrive. Cancelled sailings are the carriers’ first defence, and Drewry’s own numbers say they are not yet enough.
What to watch
- Third-quarter results, the first to include the September return to Suez.
- Blank sailings. Drewry expects 58 of 712 East-West departures between 28 September and 1 November to be cancelled, 8%. A rising share would mean carriers are defending rates by idling ships.
The disruption that made the second quarter is the one the return to Suez is ending. Shippers see it first in rates. Shareholders will see it in the third-quarter numbers.
Figures in this piece
Those the text states in the same form also stand in the margin beside it.
- $935m ($229m a year earlier)Maersk Ocean EBIT, Q2. WorldCargoNews
- $4,468/40ft, -1% w/wDrewry World Container Index. Drewry, via DCN
- Almost 14m TEU, two-fifths of fleetContainer ship orderbook. Alphaliner, via Middle East Observer
Sources
Filed under Red Sea.
A number here looks wrong? Send a correction. How corrections are handled.
Get it by email
New analysis and notes, at most once a week. The address is used for nothing else, and one reply takes you off the list. Privacy notice.